The space economy is the full chain of businesses and government programs that build, launch, operate and use technology in orbit, from rockets and satellites to the GPS signals on your phone and the missile-warning systems that protect nations. The Space Foundation estimates it reached $686 billion in 2025.
But let’s be honest: for investors, the challenge isn’t finding space stories—Wall Street is already flooded with hype. The real challenge is cutting through the noise to identify which parts of the industry actually make money, which ones are simply burning cash, and where the regulatory or technical risks hide.
This guide breaks the space economy into four layers (launch, satellites, data and defense) and explains the financial realities of each one in plain English.
Key Takeaways
- The global space economy reached roughly $686 billion in 2025, according to the Space Foundation, and about 79% of that was commercial activity rather than government spending.
- Launch is the gateway, but satellites and the services are the actual cash cows generating most of the commercial revenue.
- Defense acts as a reliable financial anchor, providing steady, government-funded revenue and capturing a growing share of public space budgets.
- Estimates of the industry’s size vary widely simply because Wall Street analysts define the “space economy” differently.
- Many pure-play space companies are young, unprofitable, and highly volatile, meaning proper position sizing matters far more than a catchy narrative. If you are looking for specific market alternatives, check out our curated list of the best space stocks to buy now.
What Is the Space Economy?
The space economy covers every activity that creates value from space or for space. Analysts usually split it into two groups. The upstream segment focuses on hardware, including designing and manufacturing rockets, satellites and ground equipment, plus the launch services that carry them to orbit. The downstream segment is all about commercial execution, covering products and services that use satellites once they are working: broadband internet, satellite television, navigation, weather forecasting and Earth imagery.
To be fair, a third, much larger idea frequently muddies the waters in headlines: the “space-enabled” economy. That term includes industries that depend on satellite signals without being space companies themselves, such as ride-hailing, precision farming, shipping and financial networks that rely on GPS timing.
This overlap is why one article may quote $600 billion while another claims nearly $2 trillion—a long-term outlook popularized by the McKinsey & World Economic Forum study. They are fundamentally measuring different things, so as an investor, you must always check the definition before comparing numbers.
How Big Is the Space Economy?
Sizing up this market is notoriously tricky. Several organizations track the industry, and their figures vary wildly based on scope. The table below breaks down the most widely cited estimates.
| Source | Estimate | What it covers |
| Space Foundation | $686 billion in 2025, up 12% from 2024 | Commercial revenue plus government space budgets |
| Novaspace | About $626 billion in 2025 | Upstream and downstream space activity |
| Space Foundation outlook | Could pass $1 trillion as soon as 2032 | The same narrow definition, projected forward |
| McKinsey and World Economic Forum | $1.8 trillion by 2035 | A broader view that includes space-enabled industries |
According to the Space Foundation, commercial activity accounted for roughly $544 billion of the 2025 total, while 53 national governments together spent close to $141 billion, a 7.4% year-over-year bump. In other words, private enterprise now captures nearly four out of every five dollars moving through the industry.
Layer 1: Launch, the Gateway to Orbit
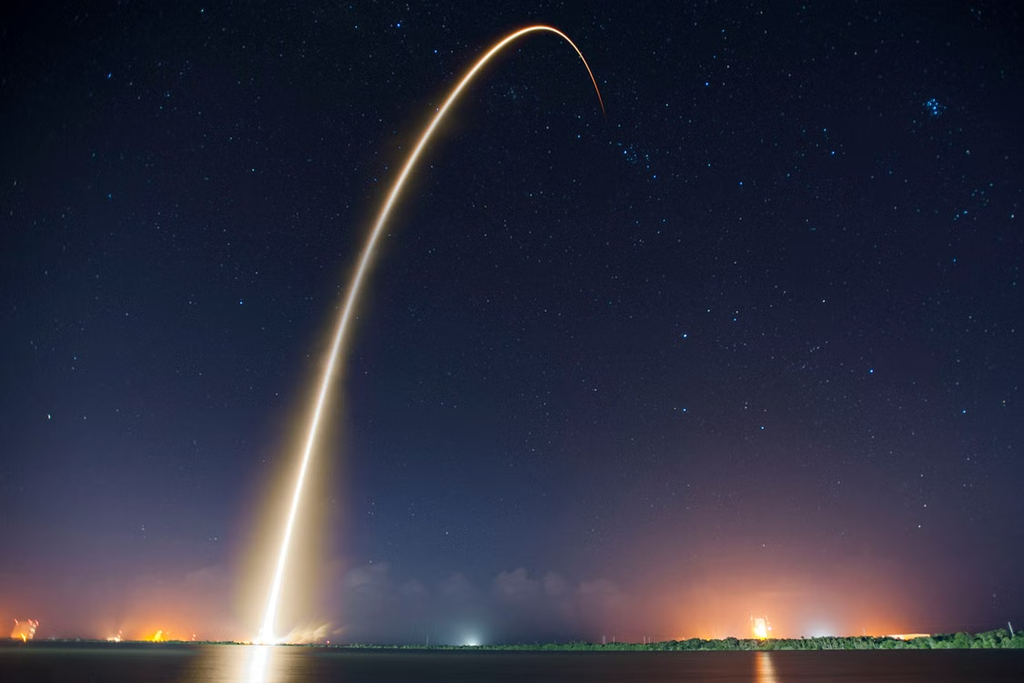
Nothing in space happens without a rocket. Launch companies sell a transportation service, charging a premium to ferry satellites, cargo, and crews to orbit. Global orbital launch attempts hit a record of roughly 320 in 2025, with a single player completely dominating the field. SpaceX flew 165 Falcon 9 missions that year—commanding about 85% of all U.S. launches—and a massive 123 of them carried its own Starlink satellites.
The key innovation here is raw reusability. Traditional rockets were thrown away after one flight. Falcon 9’s first stage lands and flies again, slashing the cost of reaching low Earth orbit from tens of thousands of dollars per kilogram in the Space Shuttle era to a few thousand dollars today. SpaceX is now pushing the envelope with Starship, a much larger, fully reusable system still in development. Other contenders include United Launch Alliance, Blue Origin, and Rocket Lab, which flies the small Electron rocket and is developing the larger Neutron.
Here is the blind spot for many new investors: launch services themselves are a relatively small revenue pool, hovering in the low tens of billions of dollars a year. Launch matters not because it’s a massive cash generator, but because it makes everything else possible. That said, it’s a brutally hard business. Rockets fail, schedules slip, and development relentlessly burns through capital.
Layer 2: Satellites, Where Most Commercial Revenue Is Made
Satellites represent the largest commercial piece of the space economy, heavily driven by communications and broadband. The best example on Wall Street right now is Starlink. SpaceX reported crossing 10 million Starlink subscribers in February 2026, skyrocketing from about 4.6 million at the end of 2024. That kind of recurring subscription revenue offers a predictable cash flow that looks very different from the one-time project fees that defined the old satellite industry.
Competition is intensifying rapidly. Amazon is building its own low-Earth-orbit broadband network, Project Kuiper/Amazon Leo. AST SpaceMobile is pursuing satellites that connect directly to ordinary smartphones, while several mobile carriers have partnered with satellite providers to close lucrative coverage gaps.
The economics are attractive when they work, since one satellite network can serve millions of customers with high operating leverage. But building a constellation requires billions of dollars in upfront capital before meaningful revenue arrives, and operators must manage radio-spectrum rights, government approvals, and the growing problem of orbital debris.
Layer 3: Data, Turning Orbit Into Information
Satellites do far more than relay signals—they act as massive data harvesters.
Earth-observation companies photograph the planet daily, packaging raw imagery and analysis for enterprise clients tracking real-time ground changes. Farmers monitor crop health, insurers assess disaster damage, energy companies watch infrastructure, and governments track activity in hard-to-reach places. Planet Labs is a prominent public player selling subscription access to its satellite imagery archive and daily data updates.
The core appeal of the data layer lies in its software-like scalability: once the hardware is operational, selling the same imagery to multiple customers yields exceptionally high margins.
However, the commercial headwinds are real: heavy customer concentration (governments are often the largest buyers), agonizingly long sales cycles, and stiff competition from free public datasets or rival networks with identical capabilities.
Layer 4: Defense, the Government Buyer
Governments are the foundational customer of the space industry, and defense is taking a growing share of their spending. Modern militaries depend on satellites for missile warning, secure communications, navigation, and surveillance. The U.S. Space Force and other agencies are steadily procuring large numbers of satellites, strategically awarding national-security launch contracts across multiple providers to maintain market competition.
Large proposals can completely reshape industry demand. The Golden Dome missile-defense initiative announced in 2025 is a prime example, as it relies heavily on space-based sensors and interceptors, though its final scope, funding, and timeline remain uncertain.
Traditional defense giants—including Lockheed Martin, Northrop Grumman, L3Harris, RTX, and Boeing—build much of this hardware, meaning space remains a critical, yet diversified segment within their broader corporate portfolios.
Defense revenue tends to be significantly steadier than consumer demand, buoyed by multi-year contracts funded by federal budgets. However, those budgets are ultimately political. Programs can be delayed, canceled, or cut, and fixed-price contracts have recently inflicted painful losses on major contractors when costs ran over.
The Four Layers at a Glance
| Layer | How it makes money | Example public companies | Main risk |
| Launch | Per-mission fees to lift payloads to orbit | SpaceX (SPCX), Rocket Lab (RKLB) | Failures, delays and heavy capital needs |
| Satellites | Subscriptions, wholesale capacity and hardware sales | SpaceX (SPCX), AST SpaceMobile (ASTS) | Large up-front cost, competition and regulation |
| Data | Imagery and analytics subscriptions | Planet Labs (PL) | Government concentration and free alternatives |
| Defense | Government contracts for satellites, launch and sensors | Lockheed Martin (LMT), Northrop Grumman (NOC), L3Harris (LHX) | Budget politics and cost overruns |
Public Versus Private: Who Can You Actually Buy?
For years, the crown jewel of the industry was completely off-limits to retail investors. That changed on June 12, 2026, when SpaceX began trading on the Nasdaq under the ticker SPCX in what clenched the title as the largest initial public offering in history, priced at $135 per share. Predictably, its shares have been volatile since the debut—a stark reminder for investors that a famous brand name is not a proxy for a safe investment.
Beyond SpaceX, the public investable universe includes launch providers, spacecraft manufacturers, satellite operators, imagery firms, and defense giants. However, several key heavyweights, like Blue Origin, remain private. Many of the smaller listed space companies are speculative, early-stage plays with limited profits, meaning their valuations can swing sharply on a single launch, government contract, or earnings report.
How Space Fits Into a Diversified Portfolio
If you own a broad U.S. index fund, you likely already hold some indirect exposure. The S&P 500 bundles large aerospace and defense companies, while several big tech giants heavily utilize satellite infrastructure. However, that exposure is highly diluted—it is a far cry from owning a pure-play space business.
Because the sector remains deeply speculative and volatile, smart investors treat it as a small “satellite” position around a diversified core rather than a portfolio foundation. How much allocation makes sense depends entirely on your goals, time horizon, and risk tolerance. Furthermore, whether a newly listed giant like SpaceX joins a major benchmark down the road depends strictly on index eligibility rules.
Key Risks to Understand
- Valuation and Hype Cycles: Space stocks often rally on headlines and crash just as fast when expectations fall short.
- Cash Burn and Dilution: Many young companies spend more than they earn and may dilute existing shareholders to fund operations.
- Technical Failure: A single failed launch or lost satellite can wipe out years of progress and revenue instantly.
- Government Dependence: Defense and civil budgets are inherently political and change with elections.
- Regulation and Space Safety: Spectrum rules, launch licensing, and orbital debris can easily bottleneck expansion.
- Concentration: A single dominant player holds outsized influence, leaving many businesses dependent on its launch capacity.
What to Watch Next
- Launch Cadence and Rocket Reusability: These metrics directly signal falling costs.
- Contract Backlog: Focus on how efficiently a company converts its backlog into real revenue.
- Cash Runway: Pay attention to how many months of operations remain before the company triggers a dilutive capital raise.
- Subscriber Metrics: Watch customer growth and revenue per user (ARPU) for satellite services.
- Defense Appropriations: Monitor major procurement decisions and federal budget approvals.
- IPO Lock-Up Expirations: Keep an eye on insider selling pressure following recent listings, tracking the conditions laid out in official lock-up agreements.
.
Frequently Asked Questions
What is the space economy?
It is the combined value of all commercial and government activity that builds, launches, operates, or relies on space technology—spanning rockets, satellites, data services, and defense systems.
How big is the space economy?
The Space Foundation estimated it at roughly $686 billion in 2025. Other analysts report different figures based entirely on whether they include broader, satellite-reliant industries.
Is SpaceX publicly traded?
Yes. SpaceX began trading on the Nasdaq under the ticker SPCX on June 12, 2026, marking one of the most anticipated public listings in market history.
Can I invest in space through an S&P 500 fund?
Only indirectly. The index holds aerospace giants and tech firms with space operations, but it does not provide exposure to pure-play, dedicated space companies.
Bottom Line
The space economy is real, large, and growing, but it is far from a monolith. Launch opens the door, satellites generate the biggest commercial revenue, data adds high-margin potential, and defense provides a reliable, deep-pocketed customer. Each layer has its own economics and unique risks. Understanding those differences is vital toward making informed decisions, whether you choose to invest in the theme or simply follow it as one of the defining industries of the decade.
On a personal note, today is my birthday! 🎉 If you want to send a gift, the best thing you can do is share this article with a fellow investor or leave your thoughts on today’s analysis in the comments below. Appreciate you reading!🚀
Disclaimer
This article is for informational and educational purposes only and is not personalized investment, financial, tax or legal advice. Nothing here is a recommendation or solicitation to buy or sell any security. All investing involves risk, including the possible loss of your entire investment, and past performance does not guarantee future results. Figures are approximate, are current as of October 2026, and may change. Before making any investment decision, I strongly urge you to do your own research and consider speaking with a licensed financial professional.
Sources and Data Notes
- Space Foundation (The Space Report and its annual State of the Global Space Economy release)
- McKinsey and the World Economic Forum’s analysis of the space economy
- Space Economy Institute – Market Analysis: Worth $613 Billion and Heading Toward $1 Trillion
- Novaspace’s Space Economy Report
- Space Foundation – The State of the Global Space Economy Full Report (July Release)
- Orbital Radar – Complete 2025 Orbital Launch Database and Statistics
- Space.com – SpaceX Annual Flight Analysis: 165 Orbital Missions and Falcon 9 Records
- SpaceX’s Starlink progress report
- Amazon Official Newsroom – Corporate Announcement: Project Kuiper Becomes Amazon Leo
- Space.com launch tracking
- SpaceX initial public offering
Written by L.Gomez · Last updated: October 16, 2026